
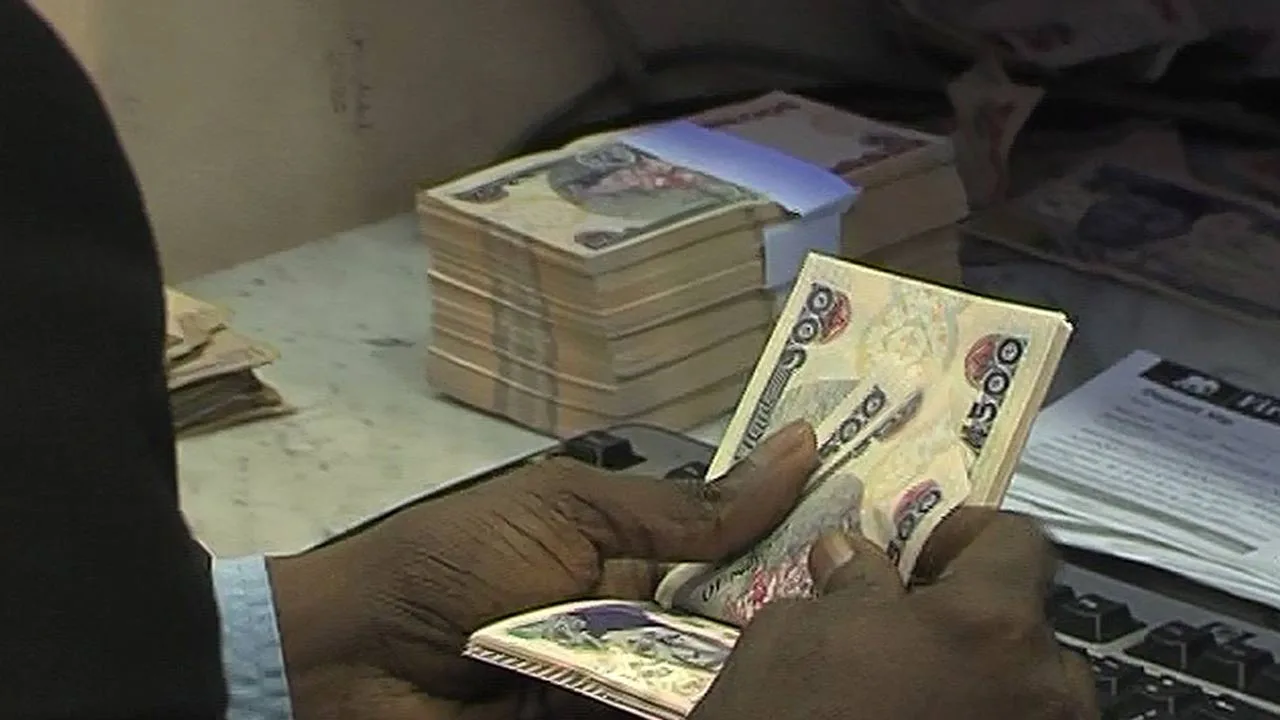
The Federal Government says beneficiaries of its ₦50,000 NERSI relief programme will receive the full amount without deductions.
However, some recipients may find that the cash they collect from a Point of Sale (POS) agent is less than the balance originally credited to their wallets.
The difference can arise from ordinary withdrawal charges rather than a deduction by the government.
Understanding this distinction is important because beneficiaries may otherwise mistake transaction costs for missing grant money.
What exactly did the government promise?
According to the official NERSI FAQ, the full ₦50,000 is credited to a selected beneficiary’s mobile wallet.
The ministry says accepting and receiving the support is free.
Beneficiaries are not required to pay registration, approval or processing fees.
However, the same guidance acknowledges that POS agents may charge their usual withdrawal fees.
This creates an important difference between the amount credited and the cash eventually collected.
How can ₦50,000 become less at a POS terminal?
Consider a hypothetical beneficiary whose wallet has been credited with ₦50,000.
If a POS agent charges ₦500 for a withdrawal and the charge is deducted from the available balance, the recipient may collect ₦49,500.
If the fee is paid separately, the beneficiary may receive ₦50,000 in cash but still incur an additional expense.
These examples are illustrative. They are not government-approved NERSI withdrawal tariffs.
The actual cost depends on the agent’s charges and the transaction arrangement.
Is a POS withdrawal fee illegal?
The ministry does not say that every POS withdrawal fee is prohibited.
Instead, it advises beneficiaries to ask about charges before withdrawing.
This means recipients should distinguish between an ordinary, disclosed transaction fee and someone demanding money to release the grant.
A person claiming that beneficiaries must pay an activation fee before receiving NERSI is contradicting the government’s rules.
Can beneficiaries avoid POS charges?
The programme allows recipients to access money through their wallets.
Depending on the provider and the services available, beneficiaries may be able to make transfers or payments without immediately converting the entire balance to cash.
However, ordinary transaction charges may still apply.
The ministry has not promised that every possible financial transaction involving the grant will be free.
Recipients should compare available options before deciding how to access their money.
What if an agent gives less cash than agreed?
The beneficiary should first establish whether the difference represents a disclosed transaction fee or an unexplained shortage.
For example, if an agent agrees to provide ₦49,500 after a ₦500 charge, that arrangement differs from promising ₦49,500 and handing over ₦48,000.
Recipients should count cash before leaving and retain transaction records.
If the amount is incorrect, they should raise the issue immediately and contact their financial provider where necessary.
What if the transaction fails but the wallet is debited?
A failed withdrawal accompanied by a debit requires investigation.
The beneficiary should avoid repeatedly authorising transactions without confirming their status.
They should keep the transaction reference and report the issue through the provider’s official support channel.
The ministry does not publish a universal refund timetable for every failed POS transaction.
Therefore, beneficiaries should not rely on unverified promises about automatic reversal periods.
Why small charges matter
For someone receiving emergency financial assistance, even modest transaction costs can reduce the value of the support.
A ₦500 charge represents one per cent of a ₦50,000 grant.
A ₦1,000 charge represents two per cent.
If a beneficiary makes several withdrawals, the combined cost may become more significant.
This is why the decision to withdraw in instalments or in one transaction should take account of actual fees and personal security.
How can recipients protect their money?
Beneficiaries should verify their balances before visiting an agent, agree on charges beforehand and avoid sharing PINs or OTPs.
They should also check transaction confirmations rather than relying exclusively on verbal assurances.
The ministry’s promise of a full ₦50,000 credit remains important.
However, it does not eliminate the need to understand the costs of accessing that money.
The government promises ₦50,000 without programme deductions, but ordinary financial transaction charges can affect the amount beneficiaries ultimately retain.