CBN Interest Rate Cut: 5 Things That Could Change for Nigerians

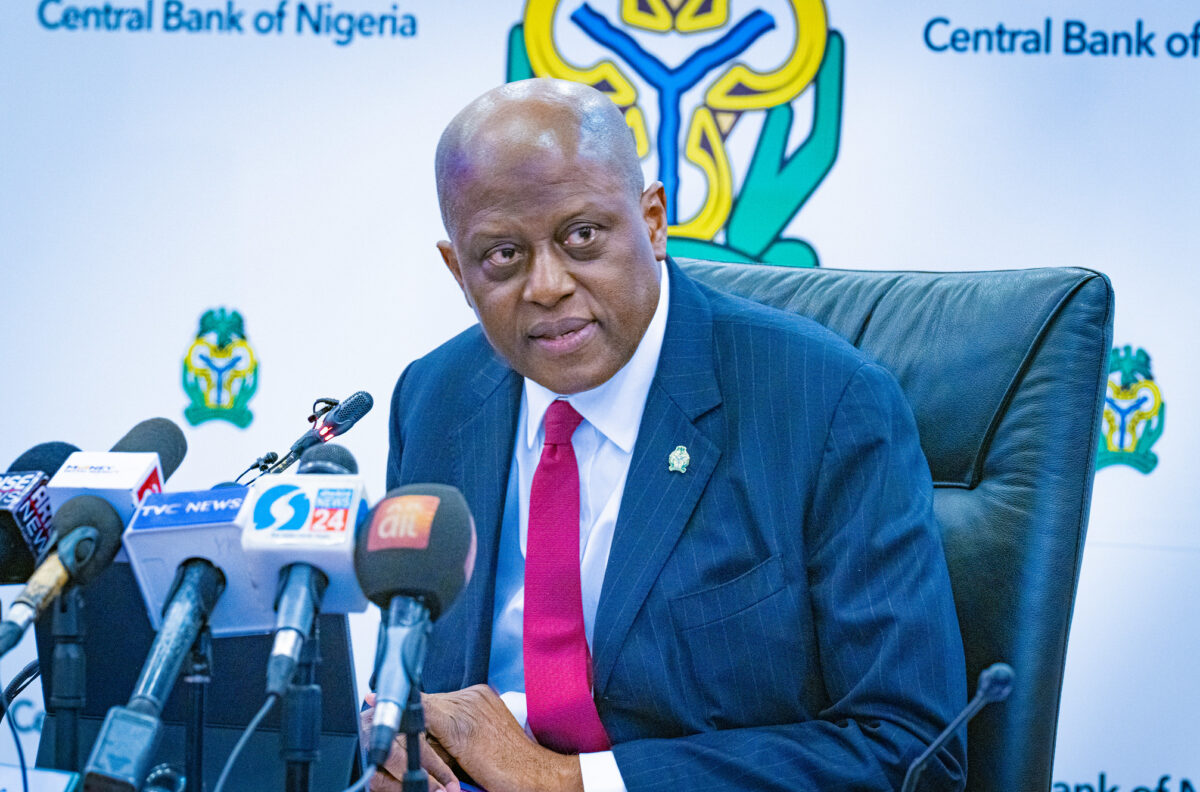
The Central Bank of Nigeria (CBN) has cut its benchmark interest rate from 26.5% to 23%, a major change that could affect how Nigerians borrow, save, invest and run businesses.
The decision was announced after the Monetary Policy Committee’s 307th meeting in Abuja on Tuesday, September 22, 2026. The 3.5 percentage-point reduction is the largest adjustment in the current monetary policy cycle.
However, the new 23% rate does not mean Nigerians will suddenly start getting bank loans at 23%. The CBN has described the decision as an operational reset aimed at improving the transmission of monetary policy to the financial system.
Here are five things that could change for Nigerians.
1. Bank loans could become cheaper
One of the biggest questions following the CBN decision is whether commercial banks will reduce the interest rates charged on loans.
The Monetary Policy Rate, or MPR, is an important signal for interest rates in the financial system. When it falls, borrowing costs can come under downward pressure, although banks do not automatically reduce their lending rates by the same amount.
This distinction is important because the CBN has not ordered banks to price every loan at 23%.
The CBN said the latest adjustment was partly aimed at fixing a gap between its previous policy rate and rates prevailing in the interbank market. Governor Olayemi Cardoso said the recalibration was intended to strengthen monetary policy transmission and restore the MPR as the main signal for interest rates.
This means borrowers may eventually benefit if the reduction feeds through to commercial lending rates.
For individuals with existing loans, however, the impact will depend on the terms of their agreements and how their lenders adjust their rates. New borrowers may also see changes if banks lower their lending rates in response to the new monetary environment.
2. Businesses could get some relief from high borrowing costs
The rate cut could also be important for Nigerian businesses that depend on bank financing.
Manufacturers, traders, farmers, construction companies and other businesses often need credit to buy equipment, finance inventory, pay suppliers or expand operations.
High interest rates can make such borrowing expensive and discourage companies from taking on new loans. The Centre for the Promotion of Private Enterprise said the latest reduction could provide relief to businesses in manufacturing, agriculture, construction and logistics, where financing costs have been a constraint on investment and working capital.
But the effect will depend on how quickly commercial banks transmit the lower policy rate to customers.
The Nigeria Employers’ Consultative Association also welcomed the reduction, describing it as a significant adjustment after a prolonged period of tight monetary conditions.
For small businesses, therefore, the key issue will not simply be that the MPR has fallen. What matters is whether banks actually offer cheaper and more accessible credit.
3. Returns on savings and investments could change
The rate environment also matters to people who keep money in interest-bearing accounts or invest in fixed-income products.
When interest rates are high, banks and other financial institutions generally have more room to offer relatively attractive returns on some savings and investment products.
A lower policy rate can put downward pressure on such returns over time.
That does not mean every savings account or investment will immediately pay less. The actual effect will depend on the product, the financial institution and broader market conditions.
For Nigerians who rely on interest income, the important development to watch is how banks and the wider fixed-income market respond to the new MPR.
In other words, the rate cut could benefit borrowers while creating a different environment for savers and investors.
4. Businesses may find it easier to invest and expand
Lower financing costs could eventually influence investment decisions.
A company considering whether to purchase new machinery, open another branch, increase production or hire more workers may be more willing to proceed if the cost of borrowing falls.
The potential benefit goes beyond companies that take loans directly. If financing becomes more affordable across parts of the economy, businesses could have more room to increase production and working capital.
The CPPE said the CBN’s decision could reduce financing costs, support investment and stimulate economic growth.
However, this is a potential effect rather than an immediate outcome.
Banks still have to assess borrowers, determine their own lending rates and manage their funding and risk costs. So the CBN’s decision creates room for cheaper credit, but it does not guarantee that every business will immediately receive cheaper financing.
5. The cost of living will not automatically fall
The CBN’s rate cut should not be confused with an immediate reduction in the prices of food, transport, rent or other household expenses.
Nigeria’s headline inflation fell to 15.39% in August 2026 from 15.43% in July, while food inflation declined from 20.31% to 19.57%. The CBN said the improvement in inflation, exchange-rate conditions and other macroeconomic indicators helped create room for the latest policy adjustment.
But lower interest rates do not directly determine the prices of individual goods.
The possible effect is more indirect. If cheaper credit encourages businesses to produce more, invest and expand, it could support economic activity and supply over time. At the same time, the CBN will still have to monitor inflation and liquidity to prevent renewed price pressures.
The central bank has also warned that election-related spending and geopolitical tensions could create fresh inflation risks.
What Nigerians should watch next
The immediate headline is that the CBN has reduced the MPR to 23%.
The more important question for households and businesses is what happens after the announcement.
Banks’ lending rates, deposit rates and other market rates will show whether the new policy rate is actually being transmitted through the financial system.
The CBN itself said the latest move was a reset and recalibration rather than a shift away from its restrictive monetary policy stance. The bank retained the Cash Reserve Requirement at 45% for deposit money banks, 16% for merchant banks and 75% for non-Treasury Single Account public-sector deposits.
So, while the 23% MPR could eventually make borrowing cheaper and support business activity, Nigerians should not expect an overnight transformation in loan rates or the cost of living.
The next stage will be how banks, financial markets, businesses and consumers respond to the new interest-rate environment.
Frequently Asked Questions
What is Nigeria’s new interest rate?
The CBN has reduced the Monetary Policy Rate from 26.5% to 23% as of September 22, 2026.
Will bank loans immediately become 23%?
No. The MPR is a benchmark policy rate and does not mean commercial banks must charge customers 23% on loans.
Why did the CBN cut the interest rate?
The CBN said the move was an operational reset designed to improve monetary policy transmission, against a backdrop of easing inflation and improved macroeconomic conditions.
Will the rate cut reduce food prices?
Not immediately. The MPR can influence economic activity and financing conditions, but food prices are affected by several factors, including supply, transport, exchange rates and production costs.
How could businesses benefit from the rate cut?
If commercial lending rates fall, businesses could potentially access financing at lower costs, giving them more room for working capital, investment and expansion.